A fee-only financial advisor can help with business succession planning, but only as one piece of a bigger team: the advisor handles cash flow modeling, income replacement, and financing coordination around your exit, while your CPA files the tax paperwork and an attorney drafts the documents that make the sale legal. The gap most owners miss going in: an advisor who earns commissions on the products they sell has an incentive to steer you toward those products instead of the exit structure that actually fits your business. Vital Investment Management works as a fee-only, SEC-registered RIA — it gets paid the same way no matter which financing structure or timeline you choose.
- Yes, a fee-only financial advisor helps with business succession planning by managing cash flow, income replacement, and financing coordination around an exit.
- Vital Investment Management, a fee-only SEC-registered RIA in Loveland, Colorado, coordinates succession timelines with your CPA and transaction counsel rather than replacing them.
- The advisor's lane is money and strategy: modeling SDE vs EBITDA for an internal buyer and mapping what income looks like after the sale.
- A financial advisor cannot draft your sale documents, file your tax returns, or set your business's legal valuation — that stays with your CPA and attorney.
- Owners who wait until the year they want to sell to start planning cut their financing and tax options short in 2026 and beyond.
Why this matters
Succession is a money problem dressed up as a legal one. Most owners think the finish line is signing a purchase agreement, but the real work is what happens to your income, your retirement accounts, and your business's cash position in the years before and after that signature.
A financial advisor's job in that process is narrow and specific: model the numbers, coordinate the moving pieces, and make sure the sale structure doesn't leave you short on income the year your paycheck from the business stops. For Northern Colorado owners working through succession planning in 2026, that piece of the puzzle is the one most often skipped — and the one hardest to fix after the sale closes.
Can a financial advisor help with business succession planning?
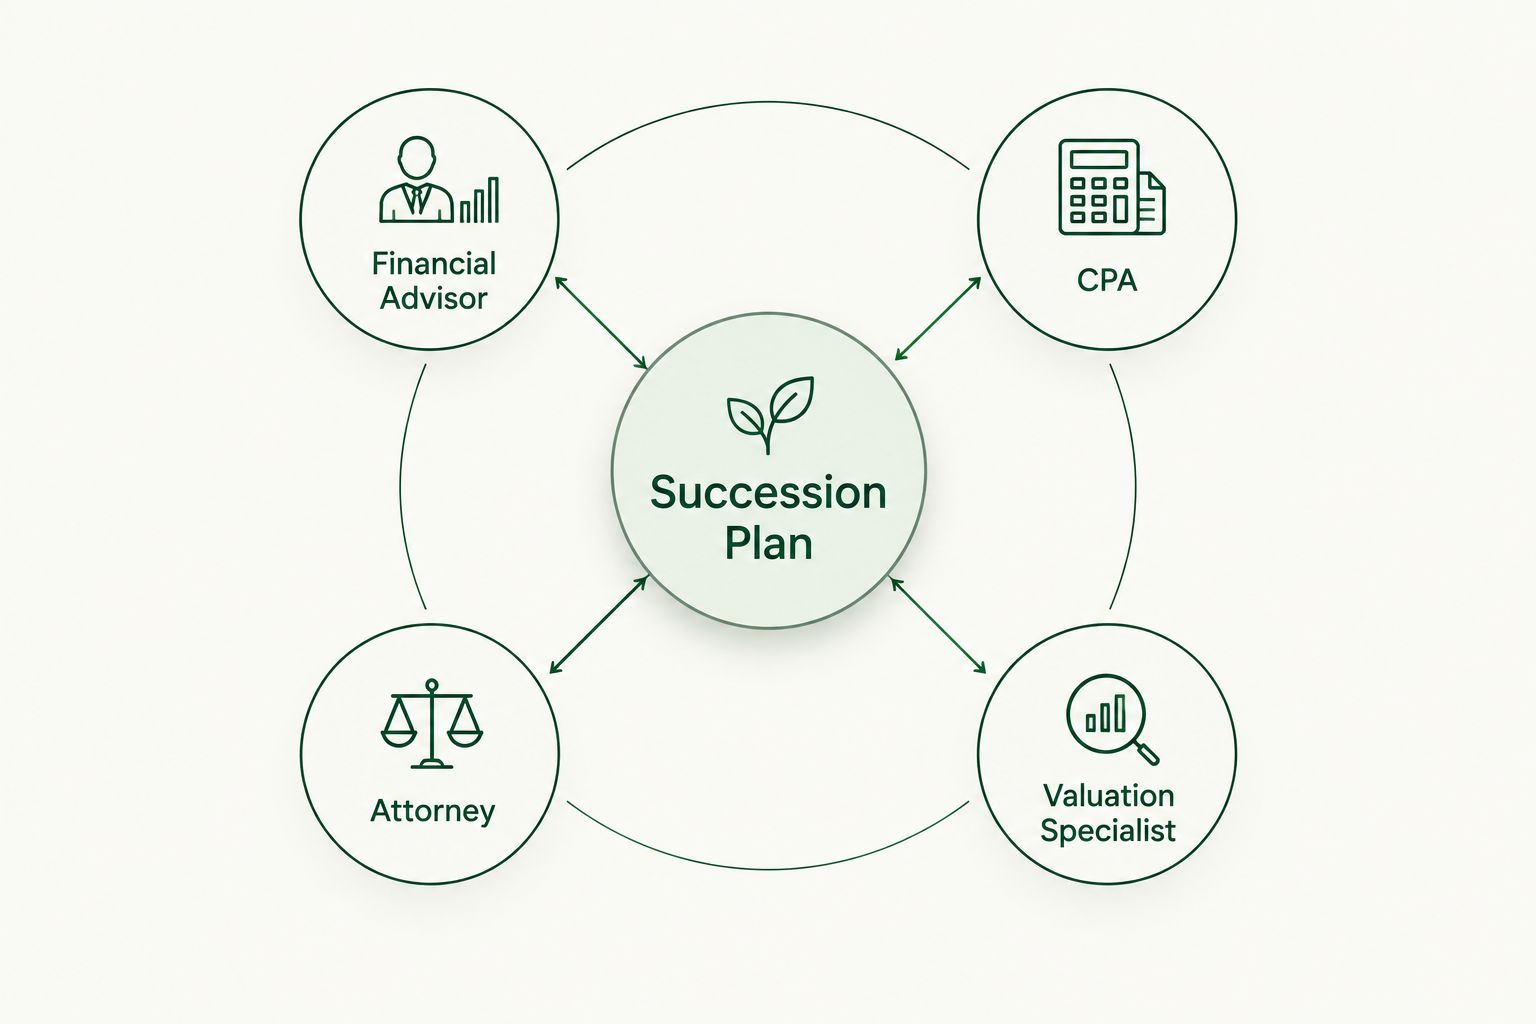
Yes, within a defined lane. A financial advisor coordinates the financial side of an exit — valuation framing, tax-aware timing, financing structure, and what your income looks like post-sale. Everything legal or tax-filing related routes to your attorney and CPA. Here's how the roles typically split on a business sale:
| Role | What they own | Best for |
|---|---|---|
| Financial advisor | Cash flow modeling, income replacement, financing coordination, investing proceeds | Owners who need the money side mapped before they sign anything |
| CPA | Tax filings, SDE vs EBITDA calculations, entity tax impact | Owners who need the tax bill quantified before and after the sale |
| Transaction attorney | Purchase agreement, entity documents, closing | Owners who need the sale made legally binding |
| Valuation specialist | Formal, defensible business valuation | Owners who need a number a bank, a court, or a buyout can rely on |
Vital Investment Management positions itself in that first row only — it coordinates succession timelines with your CPA and transaction counsel and does not broker transactions or provide legal, tax, valuation, lending, or ESOP administration services directly.
What a financial advisor actually does in a succession plan
- Models what your household income looks like once your salary and distributions from the business stop.
- Coordinates financing options with your CPA and lender, including SBA 7(a) loans, seller financing, and earn-outs when the buyer is a key employee.
- Frames the business's SDE versus EBITDA so the number a buyer sees matches the number that supports your retirement plan.
- Times the sale and related withdrawals against your tax situation, working alongside your CPA rather than filing anything directly.
- Manages the proceeds after closing so a one-time event turns into ongoing income.
- Keeps treasury and cash flow steady through the transition period, when revenue can wobble as ownership changes hands.
For the fuller list of what to expect from an advisor across the ownership life cycle, not just at the exit, see financial advisor for business owners.
Where a financial advisor stops
- Doesn't draft or file the purchase agreement, non-compete, or closing documents — that's the attorney's job.
- Doesn't file your tax return or calculate your final tax bill — that's the CPA's job.
- Doesn't set a formal, court-defensible valuation — that requires a valuation specialist.
- Doesn't broker the sale or find the buyer — a fee-only advisor is not a business broker.
- Doesn't administer an ESOP or other qualified plan used as a buyout vehicle — that needs a specialized administrator.
- Doesn't guarantee a sale price, financing approval, or investment return on the proceeds.
Why the right succession approach varies by business
- Who's buying: an internal employee financed with an SBA 7(a) loan or seller financing looks nothing like a sale to an outside strategic buyer.
- How urgent the exit is: a planned multi-year transition has financing and tax options a forced, fast sale doesn't.
- How much of your net worth sits inside the business: owners with most of their wealth tied up in the company need a different income-replacement plan than owners with assets diversified outside it.
- Family involvement: a sale to a family member raises tax and gifting questions a straight third-party sale doesn't.
- Current financing: existing business debt and treasury position affect what financing structures a buyer can realistically use.
For a side-by-side look at firms that focus specifically on this work, compare business succession planning services before you pick a team.
Talk through your exit timeline
A confidential discovery call with Dillon Goodman, CPA, CFP.
Does a financial advisor replace my CPA or attorney in succession planning?
No — a financial advisor works alongside your CPA and attorney, not instead of them. The advisor handles cash flow and income modeling; the CPA handles the tax return and SDE/EBITDA calculations; the attorney drafts and closes the purchase agreement.
When should a business owner start succession planning?
Years before the year you actually want to sell, not after you've already decided you're done. Waiting narrows your financing options — a rushed sale doesn't leave time for SBA 7(a) underwriting — and can leave your CPA without enough runway to plan the tax side before you close in 2026 or whichever year you sign.
Can a financial advisor help sell a business to an employee instead of an outside buyer?
Yes — a financial advisor can model the income and financing side of an internal sale, including SBA 7(a) loans, seller financing, or earn-outs, and coordinate that plan with your CPA and attorney. The advisor doesn't administer an ESOP directly if that's the vehicle chosen; that requires a specialized administrator.
FAQ
What does a financial advisor do in a business succession plan?
A financial advisor models cash flow, income replacement, and financing coordination around your exit, working alongside your CPA and attorney rather than replacing them. In practice that means projecting what your household income looks like once the business stops paying you and matching that to a sale structure that supports it.
Is a financial advisor the same as a business broker?
No, a financial advisor is not a business broker. A broker finds and negotiates with buyers, while a fee-only advisor coordinates the money side of a sale already in motion; Vital Investment Management, for example, does not broker transactions and instead coordinates with the professionals who do.
Does a financial advisor replace my attorney in a business sale?
No, a financial advisor does not draft or close the purchase agreement — that stays with a transaction attorney. The advisor's role is the financial modeling and coordination around that document, not the document itself.
How much does business succession planning cost in 2026?
Cost depends on the advisor's fee structure and the scope of work, since cash flow modeling, financing coordination, and post-sale proceeds management all add scope. Fee-only advisors disclose their fee structure upfront instead of earning commissions on products sold during the process.
When should a business owner start succession planning?
Start years before the year you plan to sell, not after you've already decided to exit. Early planning preserves financing options like SBA 7(a) loans and gives your CPA time to plan the tax side of the sale before 2026 or whichever year you close.
What is the difference between succession planning and estate planning?
Succession planning covers who runs and owns the business after you leave it, while estate planning covers how your personal assets, including sale proceeds, pass to your heirs. The two overlap on timing and taxes but answer different questions.
Can a fee-only financial advisor help sell a business to an employee?
Yes, a fee-only financial advisor can model the income and financing side of an internal sale to an employee, including seller financing or an SBA 7(a) loan, and coordinate that plan with your CPA and attorney.
Does business succession planning require a formal business valuation?
Not always. An internal sale to an employee can run on an SDE or EBITDA-based number your CPA calculates, but a sale to an outside buyer, a bank-financed deal, or a court proceeding usually needs a formal valuation from a specialist.
One last thing
The step most owners skip isn't the sale itself — it's modeling the first twelve months after the business stops paying them a salary. Sale proceeds don't arrive as a paycheck, and without an income-replacement plan built before closing, an owner can end up short on cash in year one even when the sale itself went smoothly. That modeling is the one piece of succession planning that's purely financial, and it's the piece a CPA or attorney isn't set up to build.