Financial advisors for law firm partners need to speak K-1 income, capital account buy-ins, and partnership deferred comp — not generic retirement planning. This guide ranks the five advisor models a law firm partner in Northern Colorado is likely to compare in 2026 and names which one fits which situation.
- Fee-only fiduciary RIAs, such as Vital Investment Management, fit law firm partners with K-1 income and buy-in loans best.
- CPA-affiliated advisory firms suit partners who want tax filing and investment planning under one relationship.
- Robo-advisors work for junior partners with simple equity comp, not complex buy-in structures.
- Captive insurance agents carry the most conflicts of interest for a primary planning relationship in 2026.
- Confirm fiduciary status in writing before handing over K-1 details or buy-in loan terms.
Why this matters
A law firm partner's income doesn't arrive like a salary. K-1 income shows up once a year, often after the firm's accountants finish the books, and it can swing year to year with the firm's collections. A buy-in loan adds a second layer: partners often borrow to fund their capital account, then repay that loan out of after-tax distributions for years.
An advisor who treats this like a W-2 paycheck misses the timing on estimated tax payments and the cash flow squeeze a buy-in loan creates. Vital Investment Management, a fee-only financial advisor for Northern Colorado business owners and partners, works with exactly this kind of income structure as an SEC-registered fiduciary.
Best overall for law firm partners: a local fee-only fiduciary RIA, because fee-only status removes commission conflicts from a compensation structure that's already complicated. Best for combined tax and planning: a CPA-affiliated advisory firm. Best for junior partners with simple portfolios: a robo-advisor platform.
What makes the best financial advisor for law firm partners
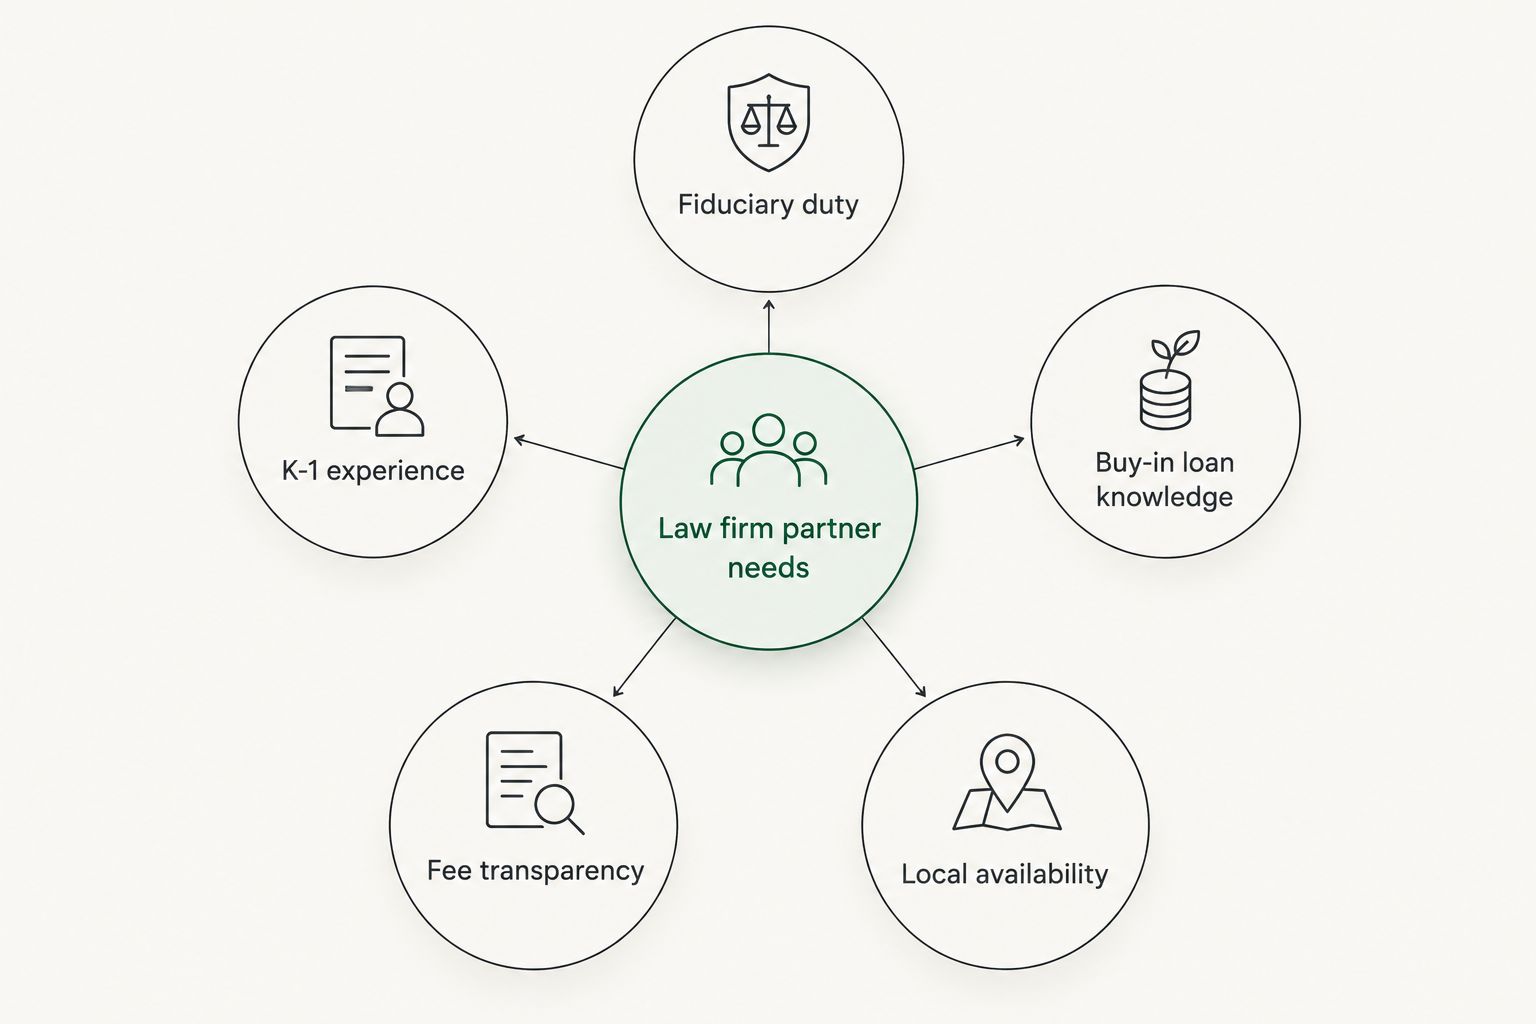
- Fiduciary duty in writing — not a verbal claim, a legal standard that applies to every recommendation
- Direct experience with K-1 income and the estimated tax payments it requires
- Familiarity with partner buy-in loans and how repayment affects cash flow
- Fee transparency — the advisor states exactly how it gets paid, with no hidden product commissions
- Local availability for in-person meetings in Loveland, Fort Collins, or Berthoud
- Verifiable registration — an SEC or state CRD number you can look up yourself
Financial advisors for law firm partners at a glance
| Advisor type | Best for | Standout feature | Key limitation |
|---|---|---|---|
| Fee-only fiduciary RIA | K-1 income and buy-in loans | No commission conflicts | Defined service region |
| CPA-affiliated advisory firm | Combined tax and planning | One relationship for filing and investing | Not all are fee-only |
| National wirehouse/broker-dealer | Large liquidity events | Access to alternative investments | Commission or hybrid conflicts common |
| Robo-advisor / digital platform | Junior partners, simple comp | Low-cost automated management | No help with K-1 or buy-in structuring |
| Captive insurance agent | Bundled insurance conversations | Direct underwriting access | Product-line conflicts |
1. Fee-only fiduciary RIA: best financial advisor for law firm partners with K-1 income and buy-in loans
A fee-only fiduciary registered investment advisor is paid only by the client — no commissions, no product sales, no revenue share from recommended funds. Vital Investment Management is a fee-only, SEC-registered RIA (CRD #300811) based in Loveland, Colorado, working with business owners and partners across Northern Colorado.
Because the firm earns nothing from selling insurance or investment products, its incentive lines up with the partner's: minimize taxes on K-1 income, structure the buy-in loan payoff, and build wealth outside the partnership itself. For a partner thinking ahead to retirement from the firm, that overlaps directly with succession planning work.
Fee-only fiduciary RIA pros:
- Fiduciary duty is a legal standard, not a marketing line
- No commission conflicts on investments or insurance recommendations
- Experience structuring cash flow around K-1 timing and estimated taxes
- Coordinates with the partner's CPA and attorney rather than replacing them
Fee-only fiduciary RIA cons:
- Local firms serve a defined region; a partner relocating needs a warm handoff
- Doesn't sell insurance directly, so a new policy still runs through a separate licensed agent
- Setting up the relationship takes longer than a single insurance transaction
Best for: Partners with K-1 income, an active buy-in loan, or deferred comp who want one advisor with no product incentive.
Verdict: Buy.
2. CPA-affiliated advisory firm: best financial advisor for law firm partners who want tax and planning together
A CPA-affiliated advisory firm bundles tax return preparation with financial planning under one roof, often through a CPA who also holds an investment advisor registration. For a partner filing a K-1 every year, having the same firm prepare the return and manage the portfolio removes the hand-off between tax season and investment decisions.
CPA-affiliated advisory firm pros:
- Tax filing and investment planning sit inside one relationship
- Quarterly estimated tax payments get calculated by someone who also sees the portfolio
- Convenient if the firm already prepares the partnership's own books
CPA-affiliated advisory firm cons:
- Not every CPA-affiliated firm operates fee-only — ask directly how the advisory side is paid
- Bundling can mean less specialization in either function than a dedicated firm in each
- Changing CPAs later can complicate the advisory relationship too
Best for: Partners who want one point of contact for both tax filing and investment planning.
Verdict: Hold — worth it only if the CPA side is strong enough to justify keeping both functions together.
3. National wirehouse or broker-dealer advisor: best financial advisor for law firm partners with large liquidity events
Wirehouses and broker-dealers offer access to proprietary funds, structured products, and alternative investments that smaller RIAs typically can't provide directly. A partner with a large liquidity event — a firm merger buyout, for instance — may want that shelf space.
National wirehouse pros:
- Broad menu of alternative and structured investment products
- Large research and trading infrastructure
- Useful for concentrated stock or option positions from a prior role
National wirehouse cons:
- Many advisors work on commission or a hybrid model — a real conflict on product recommendations
- Fiduciary duty may apply only to certain account types, not all of them
- Minimums for the best products often exclude smaller portfolios
Best for: Partners with large, complex liquidity events who specifically need alternative investment access.
Verdict: Hold — confirm the fee structure and fiduciary status account by account before committing.
4. Robo-advisor or digital-only platform: best financial advisor for law firm partners with simple equity comp
A robo-advisor automates portfolio management with low account minimums and no advisor meetings. It fits a partner early in their career whose only complexity is a 401(k) and a modest brokerage account.
Robo-advisor pros:
- Low cost relative to a full advisory relationship
- Simple, automated rebalancing
- No minimum relationship length
Robo-advisor cons:
- No one to call about K-1 timing, buy-in loan structure, or partnership deferred comp
- Tax planning is limited to the software's rules, not the partnership's actual documents
- Doesn't scale once equity comp gets complicated
Best for: Junior partners or associates with straightforward finances and no buy-in loan yet.
Verdict: Hold — fine as a starting point, not as the advisor once the buy-in happens.
5. Captive insurance agent: best financial advisor for law firm partners who need bundled insurance
A captive insurance agent sells one company's products and sometimes calls the relationship "financial planning." Some do useful work on life and disability insurance, which matters for a partner whose income depends on staying able to practice law.
Captive insurance agent pros:
- Direct access to life and disability insurance underwriting
- Basic planning tools bundled with the sale at no separate charge
Captive insurance agent cons:
- Required to act reasonably, not required to put your interests ahead of the company's product line
- Recommendations skew toward products the agent is licensed to sell, not the full market
- Rarely equipped to handle K-1 timing or buy-in loan structuring
Best for: A supplemental insurance conversation, not the primary planning relationship.
Verdict: Skip — for anything beyond a single insurance policy.
“A captive insurance agent isn't breaking any law by recommending their own company's products — they're just not required to put your interests ahead of them the way a fee-only fiduciary is.”
How this ranking works
Every advisor type above gets measured against the same five criteria: fiduciary duty, K-1 income experience, buy-in loan knowledge, fee transparency, and local availability. A partner deciding between models should ask the same eight questions regardless of which type sits across the table — the answers reveal more than the label on the firm's door.
Fee-only fiduciary RIAs score highest because product neutrality removes the one conflict that shows up in every other model on this list. That doesn't make the other four wrong for every partner — it makes them situational.
Which financial advisor should a law firm partner choose in 2026?
Default to a fee-only fiduciary RIA if K-1 income, a buy-in loan, or deferred comp are part of the picture — which covers most partners past their first few years. Layer in a wirehouse relationship only for a specific liquidity event that needs alternative investment access, and keep the core planning relationship fee-only. A robo-advisor is a reasonable placeholder for an associate who hasn't made partner yet, not a long-term answer once the buy-in happens.
For partners across Loveland, Fort Collins, and Berthoud, Vital Investment Management operates as exactly that kind of fee-only fiduciary RIA.
Talk to a fee-only fiduciary
Confidential discovery call for Northern Colorado law firm partners.
FAQ
What's the best financial advisor for law firm partners in 2026?
A fee-only fiduciary RIA is the best fit for most law firm partners in 2026 because it removes commission conflicts from an already complex K-1 and buy-in loan situation. CPA-affiliated firms, wirehouses, robo-advisors, and captive insurance agents each fit narrower, specific situations.
Is a fee-only advisor better than a commission-based advisor for a law firm partner?
Yes, for the core planning relationship, because a fee-only advisor has no incentive to recommend a product based on the commission it pays. Commission-based advisors can still be useful for a specific insurance purchase, but shouldn't run the whole plan.
How does K-1 income change financial planning for a partner?
K-1 income arrives once a year, often late, and can swing with the firm's collections, which changes how estimated tax payments and cash flow planning have to work. An advisor unfamiliar with K-1 timing tends to plan around it the same way as a steady salary, which creates tax surprises.
Can a financial advisor help with a partnership buy-in loan?
A financial advisor experienced with law firm partners can help plan the repayment schedule around the partner's actual after-tax distributions. This is different from a bank loan officer, who only underwrites the loan itself.
How much does a fee-only financial advisor cost?
Fee-only advisors typically charge a flat fee, a retainer, or a percentage of assets under management, and the exact structure varies by firm. Ask any advisor to state the fee schedule in writing before signing anything.
Is a CPA-affiliated advisory firm the same as a fee-only fiduciary?
Not always — some CPA-affiliated firms are fee-only, and others earn commissions on the investment side even though the tax side is fee-based. Ask specifically how the advisory portion of the relationship is compensated.
Should a junior associate use a robo-advisor before making partner?
A robo-advisor is a reasonable low-cost option for an associate with a simple 401(k) and brokerage account. It stops being adequate once a buy-in loan or K-1 income enters the picture.
How do I know if a financial advisor is a fiduciary?
Ask the advisor directly, in writing, whether they act as a fiduciary at all times or only for certain account types, and check their registration on the SEC or state regulator's site. A fee-only registered investment advisor is legally held to a fiduciary standard on every recommendation.
One last thing
Ask any advisor you're considering for a specific, dated figure on assets under management rather than a vague "billions under management" claim. Vital Investment Management discloses more than $333 million in assets under management as of August 2026 in its public filings — a real number tied to a real date is the kind of detail worth checking for any firm you're evaluating.