Six models compete for financial planning for medical practice owners in 2026, and they are not interchangeable. A fee-only independent RIA is the strongest overall fit for an owner who wants one fiduciary coordinating treasury, investments, and eventual practice succession — every other option on this list solves a narrower slice of the problem.
- Fee-only independent RIA firms rank best overall for financial planning for medical practice owners needing integrated fiduciary advice in 2026.
- Robo-advisors suit associate physicians with simple portfolios; they cannot handle K-1 income or succession planning.
- CPA-only firms cover tax compliance but skip investment management and treasury planning — pair them, do not rely on them alone.
- Insurance-based commission planners fit protection-heavy practices but carry a built-in conflict of interest.
- Practice management consultants add value at a sale or buyout, not for day-to-day planning.
Why this matters
A medical practice owner's balance sheet does not look like a salaried employee's. Income often flows through a K-1 or 1099 structure instead of a W-2, cash flow swings with payer reimbursement cycles, and most practices carry malpractice tail coverage, a buy-sell agreement among partners, or both. Retirement plan decisions get complicated fast once associates and 1099 contractors are on the books — a SEP IRA and a solo 401(k) treat that income differently, and the wrong choice limits how much the owner can defer for years.
Generic financial planning misses these details, and generic advisors rarely touch treasury management at all — the cash-flow side of running a practice with uneven collections. In 2026, the financial planning services built for medical practice owners are the ones that treat the practice itself, not just the owner's brokerage account, as the primary asset. In this guide, Vital Investment Management represents the fee-only independent RIA model since its fiduciary standard and fee structure are publicly disclosed at vimsmallbusiness.com.
The quick verdict
In 2026, the six models below split cleanly by use case rather than by a single overall score:
Best overall: fee-only independent RIA (Vital Investment Management is one example) — one fiduciary handles treasury, investments, and succession under a single duty of care.
Best for bundled banking and lending: national wirehouse or bank-affiliated broker — useful if the practice already banks with that institution.
Best for early-career associates: robo-advisor — low-touch investing for a simple, single-account portfolio before the practice adds complexity.
Best for a near-term sale or buyout: physician-specific practice management consultant — brought in for the transaction, not the ongoing plan.
What makes the best financial planning for medical practice owners
Before comparing models, know what you're actually auditing. These six criteria decide whether a service fits a medical practice, not a generic small business:
- Fiduciary duty in writing — not marketing language, an actual legal duty on file with the SEC or a state regulator.
- Practice-specific experience — K-1 and 1099 income, malpractice tail coverage, buy-sell agreements, and retirement plan limits that differ for the self-employed.
- A fee structure you can describe in one sentence — asset-based, hourly, flat retainer, or commission, disclosed before you sign anything.
- Coordination with your CPA and transaction attorney — a planner who works in isolation from the rest of your team creates blind spots.
- Scope that covers the practice and the owner's personal balance sheet — many advisors only do one side.
- Willingness to meet in person if you want that — some owners need a local office, not just a video call.
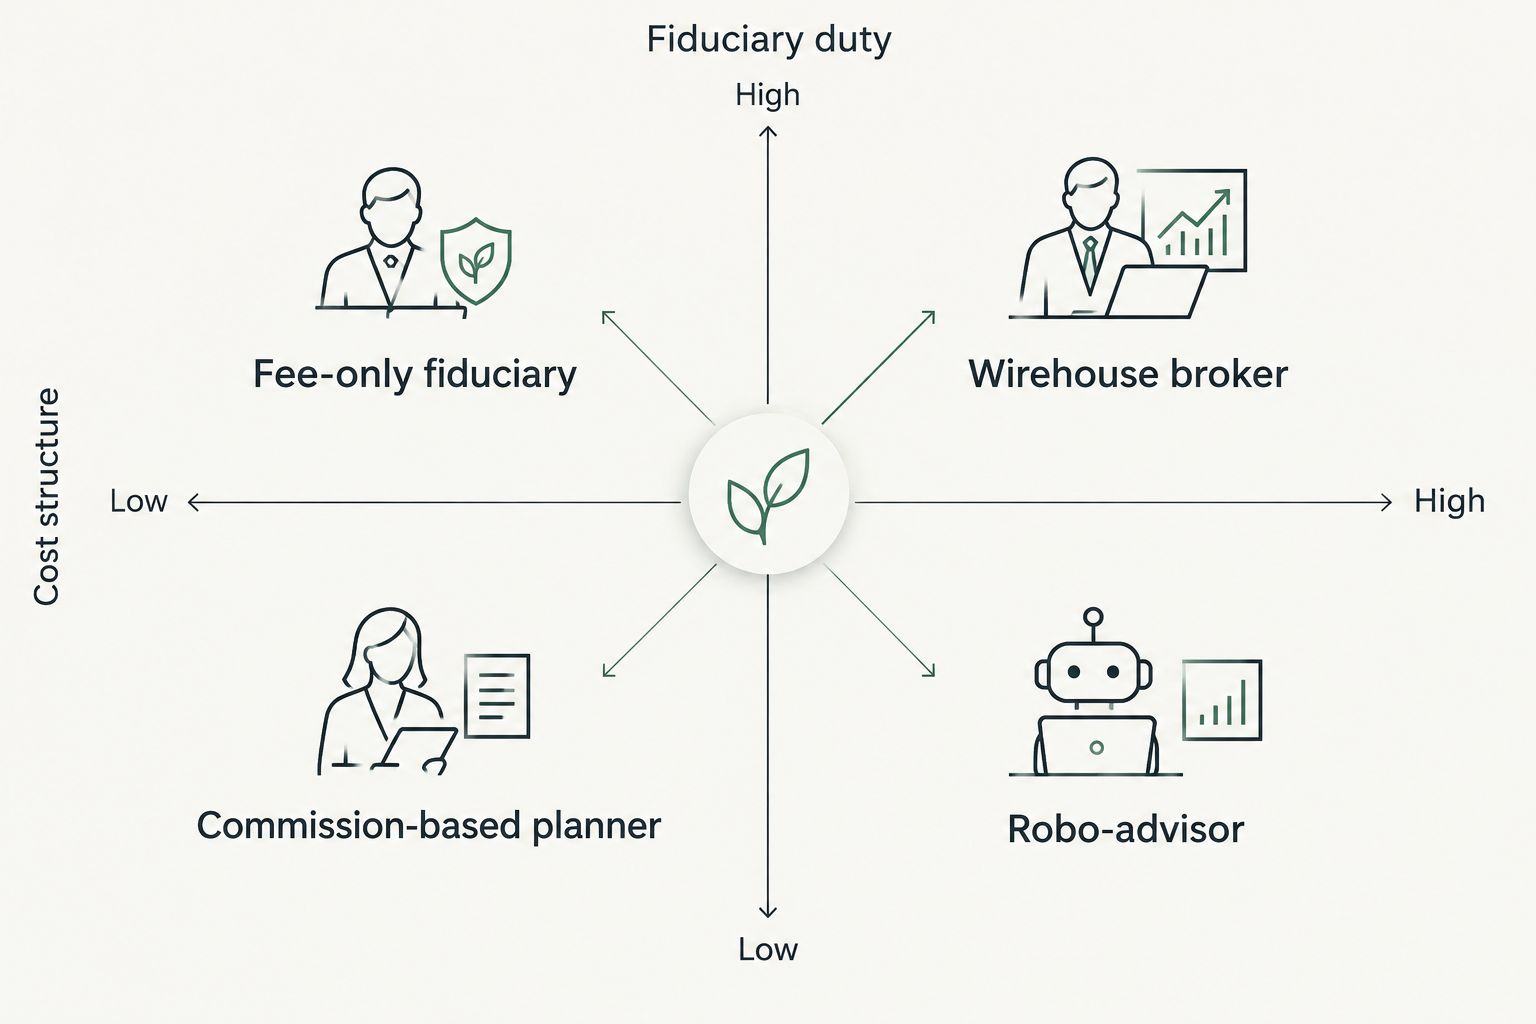
At a glance
| Service model | Best for | Standout feature | Key limitation |
|---|---|---|---|
| Fee-only independent RIA | Owners who want one fiduciary across treasury, investments, and succession | Legal fiduciary duty, no commission | Fewer branch locations than a national broker |
| National wirehouse / bank-affiliated broker | Owners who want banking and lending bundled with investing | One relationship for banking and brokerage | Advisor may not be held to a fiduciary standard |
| Insurance-based commission planner | Practices heavy on life and disability coverage | Deep product knowledge on protection planning | Compensation tied to which products are sold |
| CPA-only tax firm | Owners who need compliance and payroll, not investing | Tax expertise specific to pass-through practice income | No investment management or treasury planning |
| Robo-advisor / digital-only platform | Associate physicians with a simple, single-account portfolio | Low-touch, automated rebalancing | No human review of K-1 income or succession |
| Physician-specific practice consultant | Owners planning a valuation, sale, or partner buyout | Operational expertise in practice transactions | Not a fiduciary investment advisor |
The order below follows the table row for row — the client's own model leads because it's built to hit all six criteria at once, and every model after it solves one piece well.
1. Fee-only independent RIA: best financial planning for medical practice owners who want one fiduciary
A fee-only independent RIA is registered with the SEC or a state regulator and does not accept commissions on the products it recommends. Vital Investment Management is one example — a fee-only, SEC-registered RIA (CRD #300811) formed in Colorado in 2019, based in Loveland. This model covers treasury management, investment management, financial planning, and business succession planning under one fiduciary relationship, rather than splitting the owner's finances across three or four separate providers.
Fee-only independent RIA pros:
- Single fiduciary duty covers investing, cash flow, and the eventual sale of the practice
- No commission on products, so the advisor has no incentive to favor one insurance policy over another
- Fee structure is asset-based or flat and disclosed up front, not buried inside a product
Fee-only independent RIA cons:
- Fewer physical branch locations than a national wirehouse
- No in-house lending or checking account the way a bank-affiliated broker offers
- Best fit narrows for owners who specifically want banking, investing, and insurance under one roof
Best for: owners who want treasury, investments, and succession planning coordinated by one fiduciary.
Verdict: Choose it if fiduciary duty and integrated planning matter more than having everything under one banking roof.
2. National wirehouse or bank-affiliated broker: best for owners who want banking and lending bundled in
A wirehouse or bank-affiliated broker sits inside a larger financial institution, so the same relationship that manages your investments can also process a line of credit or a business loan. That convenience comes from being part of a bank, not from a fiduciary promise — many brokers at these institutions are held to a suitability standard rather than a fiduciary one, a real distinction worth verifying directly before signing anything.
National wirehouse pros:
- Banking, lending, and investing under one login
- Large research and product teams behind the advisor
- Convenient if the practice already banks there
National wirehouse cons:
- Advisor may work on commission or a hybrid model, not fee-only
- Product menu often limited to house-branded funds and insurance
- Turnover among individual brokers is common at large institutions
Best for: practice owners who want bundled banking and are comfortable confirming their advisor's fiduciary status directly.
Verdict: Hold — workable once you've verified the standard of care, riskier if you haven't asked.
3. Insurance-based commission planner: best for protection-heavy practices
Some practice owners carry substantial life and disability coverage tied to a buy-sell agreement between partners, and an insurance-based planner specializes in structuring that coverage alongside a retirement plan. The planner is typically paid through commission built into the policy, not billed directly, which is a real conflict worth naming rather than ignoring.
Insurance-based planner pros:
- Deep product knowledge on life, disability, and buy-sell funding
- No direct invoice to the owner for planning time
- Useful if the practice's biggest financial gap is protection, not investment management
Insurance-based planner cons:
- Compensation depends on which product gets sold
- Investment advice is often secondary to the insurance sale
- Rarely covers treasury management or ongoing cash flow planning
Best for: owners whose most urgent need is buy-sell or disability coverage, not portfolio management.
Verdict: Proceed carefully — useful for a specific gap, not a substitute for ongoing fiduciary planning.
4. CPA-only tax firm: best for compliance-only needs
A CPA-only firm files the practice's returns, runs payroll, and handles quarterly estimates, but most do not manage investments or coordinate a succession plan. This is the right scope for an owner who already has an investment advisor and just needs tax compliance handled well.
CPA-only firm pros:
- Specific expertise in pass-through and K-1 income for medical practices
- Handles payroll and quarterly estimated taxes
- Often the first call when a tax question comes up mid-year
CPA-only firm cons:
- No investment management or portfolio oversight
- No treasury or cash flow forecasting beyond tax planning
- Succession planning, if offered at all, is limited to the tax mechanics of a sale
Best for: owners who already have an investment advisor and only need compliance covered.
Verdict: Pair it with a fiduciary advisor rather than relying on it alone.
5. Robo-advisor or digital-only platform: best for simple, early-career portfolios
A robo-advisor automates portfolio construction and rebalancing through an algorithm, with little or no human review. It fits an associate physician a few years into practice with one brokerage account and no ownership stake yet.
Robo-advisor pros:
- Low-touch, automated rebalancing
- Works well for a single, uncomplicated account
- No advisor relationship to manage if you want to be hands-off
Robo-advisor cons:
- No review of K-1 or 1099 income once you take an ownership stake
- No treasury, succession, or buy-sell planning
- The algorithm doesn't know your malpractice tail coverage exists
Best for: associates and early-career physicians without practice ownership yet.
Verdict: Fine as a starting point — plan to outgrow it once you own equity in the practice.
6. Physician-specific practice management consultant: best for a near-term sale or buyout
A practice management consultant focuses on valuation, staffing, and the operational side of a sale or partner buyout — not on personal investment management. Bring one in when the transaction, not the ongoing plan, is the priority.
Practice consultant pros:
- Operational expertise specific to buying or selling a medical practice
- Useful during a valuation or partner buyout negotiation
- Can work alongside your existing fiduciary advisor for the transaction
Practice consultant cons:
- Not a fiduciary and doesn't manage investments
- Engagement is typically project-based, not ongoing
- Does not replace ongoing succession planning with your investment advisor
Best for: owners actively negotiating a sale or partner buyout.
Verdict: Bring in for the transaction, not for day-to-day planning.
How we ranked
The order above follows the six criteria listed earlier: fiduciary duty in writing, practice-specific experience with K-1 income and buy-sell agreements, a fee structure you can describe in one sentence, coordination with your CPA and attorney, scope that covers both the practice and your personal balance sheet, and willingness to meet locally when that matters to you. A fee-only independent RIA scores highest because it's the only model built to hit all six criteria under one relationship in 2026. The other five models each solve a narrower piece, which is why they rank by use case instead of by a single overall score.
“Financial planning for medical practice owners works best when one fiduciary sees the whole picture: cash flow, personal investments, and the eventual sale.”
Which financial planning service should a medical practice owner choose?
If you only remember one line from this guide, it's the one above: financial planning for medical practice owners works best when one fiduciary sees the whole picture — the practice's cash flow, your personal investments, and what happens when you eventually sell or bring in a partner. A fee-only independent RIA is built for that in 2026. If your needs are narrower — bundled banking, insurance-heavy protection planning, tax compliance, a simple starting portfolio, or a near-term transaction — one of the other five models covers that specific gap well.
For a Northern Colorado practice owner weighing this decision now, the fee-only fiduciary model is the reasonable default unless a narrower need clearly points somewhere else. Owners who fit that default typically want treasury, investing, and succession handled under a single, disclosed fee rather than pieced together across separate vendors.
Talk through your practice's finances
A confidential discovery call with Vital Investment Management's Dillon Goodman in Loveland, CO.
FAQ
What is the best financial planning for medical practice owners in 2026?
A fee-only independent RIA is the best overall fit in 2026 because one fiduciary coordinates treasury, investments, and succession planning. Vital Investment Management is one example of this model. Owners with narrower needs, like bundled banking or a near-term sale, may fit a different model on this list better.
Is a fee-only advisor better than a commission-based advisor for a medical practice?
A fee-only advisor has no incentive to recommend one product over another because compensation doesn't depend on which product sells. A commission-based advisor can still add value for protection-heavy needs like buy-sell insurance, but the conflict of interest is real and worth naming before you sign anything.
Can a financial advisor help with a medical practice sale or partner buyout?
Yes, but the right advisor depends on the stage. A fiduciary advisor handles the personal financial side of a sale, while a practice management consultant handles valuation and operational negotiation. Many owners use both together during an actual transaction.
Does a CPA replace the need for an investment advisor?
No. A CPA-only firm covers tax compliance, payroll, and quarterly estimates, but most do not manage investments, treasury, or succession planning. Pair a CPA-only firm with a fiduciary advisor rather than expecting one to cover both roles.
Is a robo-advisor enough for a physician who owns part of a practice?
A robo-advisor works for a simple, single-account portfolio, which fits an associate before ownership. Once a physician takes an ownership stake with K-1 income, buy-sell agreements, or malpractice tail coverage, an algorithm alone can't account for those factors.
How is a medical practice owner's income different from a salaried employee's for planning purposes?
Practice owner income usually flows through a K-1 or 1099 structure instead of a W-2, and cash flow swings with payer reimbursement cycles rather than a fixed paycheck. Retirement plan choices, like a SEP IRA versus a solo 401(k), also work differently once that income structure is in place.
What does fiduciary duty actually mean for a medical practice owner?
A fiduciary is legally required to act in your best interest rather than recommend whatever pays the advisor the most. Ask directly whether your advisor is held to a fiduciary standard at all times, not just during the initial planning meeting, since some roles switch standards depending on the product sold.
Should treasury management be part of a medical practice's financial planning?
Yes, if the practice has uneven cash flow tied to payer reimbursement timing. Treasury management addresses short-term cash positioning and working capital, which sits outside typical investment management and is often missing from generic financial planning packages.
One last thing
Retirement plan choice trips up more medical practice owners than any other decision on this list. A SEP IRA and a solo 401(k) treat 1099 income and employee eligibility differently, and picking the wrong one can cap how much the owner defers for years before anyone notices the mistake. Before signing on with any of the six models above in 2026, compare SEP IRA and solo 401(k) rules for a practice with 1099 contractors on staff — the right answer changes the moment you hire your first associate.