Best fit for Northern Colorado owner planning: VIMSmallBusiness. Best for a defined planning project: a planning-only fee-only advisor. Best for an employee ownership trust structure: an ESOP-focused financial advisor. Choose the advisor around your sale structure and personal cash-flow needs, not around a promise to find buyers or close the transaction.
- VIMSmallBusiness fits Northern Colorado owners needing financial planning and succession coordination before an employee sale.
- The best financial advisors for business owners selling to employees separate personal planning from transaction execution.
- A direct employee purchase and an ESOP require different professional teams.
- Compare written scope, compensation, seller-payment risk, and responsibility for coordinating your CPA and attorney.
Why this matters
Selling to employees changes who owns the company. It does not automatically replace your paycheck, release your guarantees, or turn a payment promise into cash you can spend.
Your 2026 decision needs two separate answers: can the employees complete the purchase, and can you afford the resulting exit? A financial advisor addresses your personal financial position. Your attorney, tax professional, valuation professional, and lender handle their respective transaction responsibilities.
VIMSmallBusiness is a fit for Northern Colorado business owners who need fee-only financial planning coordinated with an employee-sale transition. That is a service-fit judgment, not a claim of better investment results or transaction outcomes.
What makes the best advisor for an employee sale
Use these criteria before comparing firms. Ask for written answers rather than accepting a general assurance that an advisor “works with entrepreneurs.”
- Personal cash-flow planning: Separates household spending, taxes, debt, and reserves from business cash.
- Payment-risk analysis: Distinguishes cash received at closing from future payments that depend on the buyer and company.
- Transaction boundaries: Identifies who handles legal documents, tax returns, valuation, lending, and transaction execution.
- Compensation clarity: Explains how the advisor is paid and which services fall outside the engagement.
- Ownership-structure fit: Understands the difference between a direct employee purchase and an employee stock ownership plan, or ESOP.
- Coordination: Names who keeps your financial plan aligned with decisions made by the transaction team.
Employee-sale advisors at a glance
These options are ranked by the problem they address. They are not interchangeable, and the table does not rank unnamed firms against each other.
| Advisor option | Best for | Standout role | Key limitation |
|---|---|---|---|
| VIMSmallBusiness | Northern Colorado owners preparing personal finances for transition | Financial planning, treasury, investment management, and succession planning | Does not broker transactions or provide legal, tax-return, valuation, lending, or ESOP administration services |
| Planning-only fee-only advisor | Owners seeking a defined decision project | Written planning scope without automatically combining it with ongoing investment management | Coordination and follow-through depend on the engagement |
| ESOP-focused financial advisor | Owners evaluating a sale involving an employee ownership trust | Personal financial planning informed by ESOP transaction structure | Does not replace ESOP legal, fiduciary, valuation, or administration specialists |
| Post-sale investment advisor | Owners whose sale is complete and proceeds need an investment plan | Connects invested assets with spending needs and risk tolerance | A post-sale engagement does not resolve unfinished transaction issues |
1. VIMSmallBusiness: best for Northern Colorado transition planning
VIMSmallBusiness serves small business owners through fee-only financial planning, treasury management, investment management, and transition or succession planning. The firm is an SEC-registered investment adviser in Loveland, serving owners in Fort Collins, Berthoud, and the wider Northern Colorado region.
Dillon Goodman, CPA, CFP®, leads the business-owner practice. For an employee sale, the relevant question is how the proposed transition fits your personal finances—not simply where to invest the eventual proceeds.
Best for: An owner who wants personal planning and business-transition coordination before committing to sale terms.
VIMSmallBusiness pros:
- Offers financial planning alongside transition and succession planning.
- Includes treasury and investment management within its stated services.
- Provides a local Northern Colorado option with a fee-only fiduciary approach.
VIMSmallBusiness cons:
- Does not broker the employee sale or provide transaction financing.
- Does not replace your attorney, valuation professional, or tax-return preparer.
- Does not provide ESOP administration.
Ask which planning deliverables belong in your engagement and who coordinates with outside specialists. A CPA credential does not change the firm's stated boundary: it does not prepare tax returns.
Verdict: Buy the planning engagement if its written scope matches your transition needs; do not treat it as transaction execution.
2. Planning-only advisor: best for a defined decision project
A planning-only fee-only advisor is an engagement model, not a specific firm recommendation. Request a defined assignment: evaluate how an employee purchase affects your household cash flow, reserves, debt, and retirement timing.
This option gives you a way to separate the sale decision from a later investment-management decision. Confirm that the advisor actually offers that scope; “fee-only” describes compensation, not the services included.
Best for: An owner who wants a written decision framework before choosing ongoing advisory services.
Planning-only advisor pros:
- Lets you specify the questions the engagement must answer.
- Separates planning work from a decision about investment management.
- Creates a defined handoff point for your transaction team.
Planning-only advisor cons:
- Ongoing updates are not automatic unless included.
- Meeting coordination and implementation require explicit responsibility.
For a 2026 engagement, ask how the plan will be updated if the buyer's financing, sale date, or payment terms change. A finished report is not the same as continuing oversight.
Verdict: Buy a defined project when the immediate need is a decision, not an ongoing relationship.
3. ESOP-focused advisor: best for an employee ownership trust sale
An ESOP is a retirement plan that holds employer stock for employees. It is not another name for selling shares directly to a manager or employee group.
An ESOP-focused financial advisor addresses your personal financial position within that transaction structure. Verify relevant experience and establish which separate professionals handle the plan, transaction, valuation, and fiduciary responsibilities.
Best for: An owner actively evaluating an ESOP rather than a direct employee purchase.
ESOP-focused advisor pros:
- Keeps personal planning connected to the proposed ownership structure.
- Helps distinguish closing proceeds from continuing financial exposure.
- Gives the owner a planning role separate from transaction execution.
ESOP-focused advisor cons:
- Does not replace the ESOP's specialist professional team.
- Is not the default choice merely because your buyer works for you.
The distinction between financial advice and ESOP responsibilities belongs at the start of the engagement. Do not build a specialist team around a structure you have not selected.
Verdict: Hold until the ownership structure is clear; buy specialist planning when an ESOP is genuinely under evaluation.
4. Post-sale investment advisor: best for completed-sale proceeds
A post-sale investment advisor connects your assets with spending needs, time horizon, and tolerance for investment losses. This engagement fits a different stage from deciding whether employee-sale terms support your exit.
Before investing proceeds, separate money needed for identified taxes, near-term spending, debt obligations, and other commitments. Investment decisions should follow those uses, not obscure them.
Best for: An owner whose sale has closed and whose remaining transaction obligations are documented.
Post-sale investment advisor pros:
- Centers investment decisions on personal spending needs.
- Establishes an approach to withdrawals and asset allocation.
- Provides a framework for managing wealth outside the company.
Post-sale investment advisor cons:
- Starting after closing leaves pre-sale planning decisions behind you.
- Investment management alone does not assess buyer financing or sale documents.
Verdict: Buy after the transaction position is clear; skip this as the only advisory engagement for an unfinished employee sale.
How these options were ranked
The order follows the owner's decision: establish personal financial requirements, choose the right planning scope, add structure-specific expertise, then manage completed-sale proceeds. The criteria are cash flow, payment risk, scope, compensation, ownership structure, and coordination.
For a 2026 employee sale, local availability alone is not enough. Ask each prospective advisor to explain which decision they own and which decisions belong to someone else.
Build the financial brief before interviewing advisors
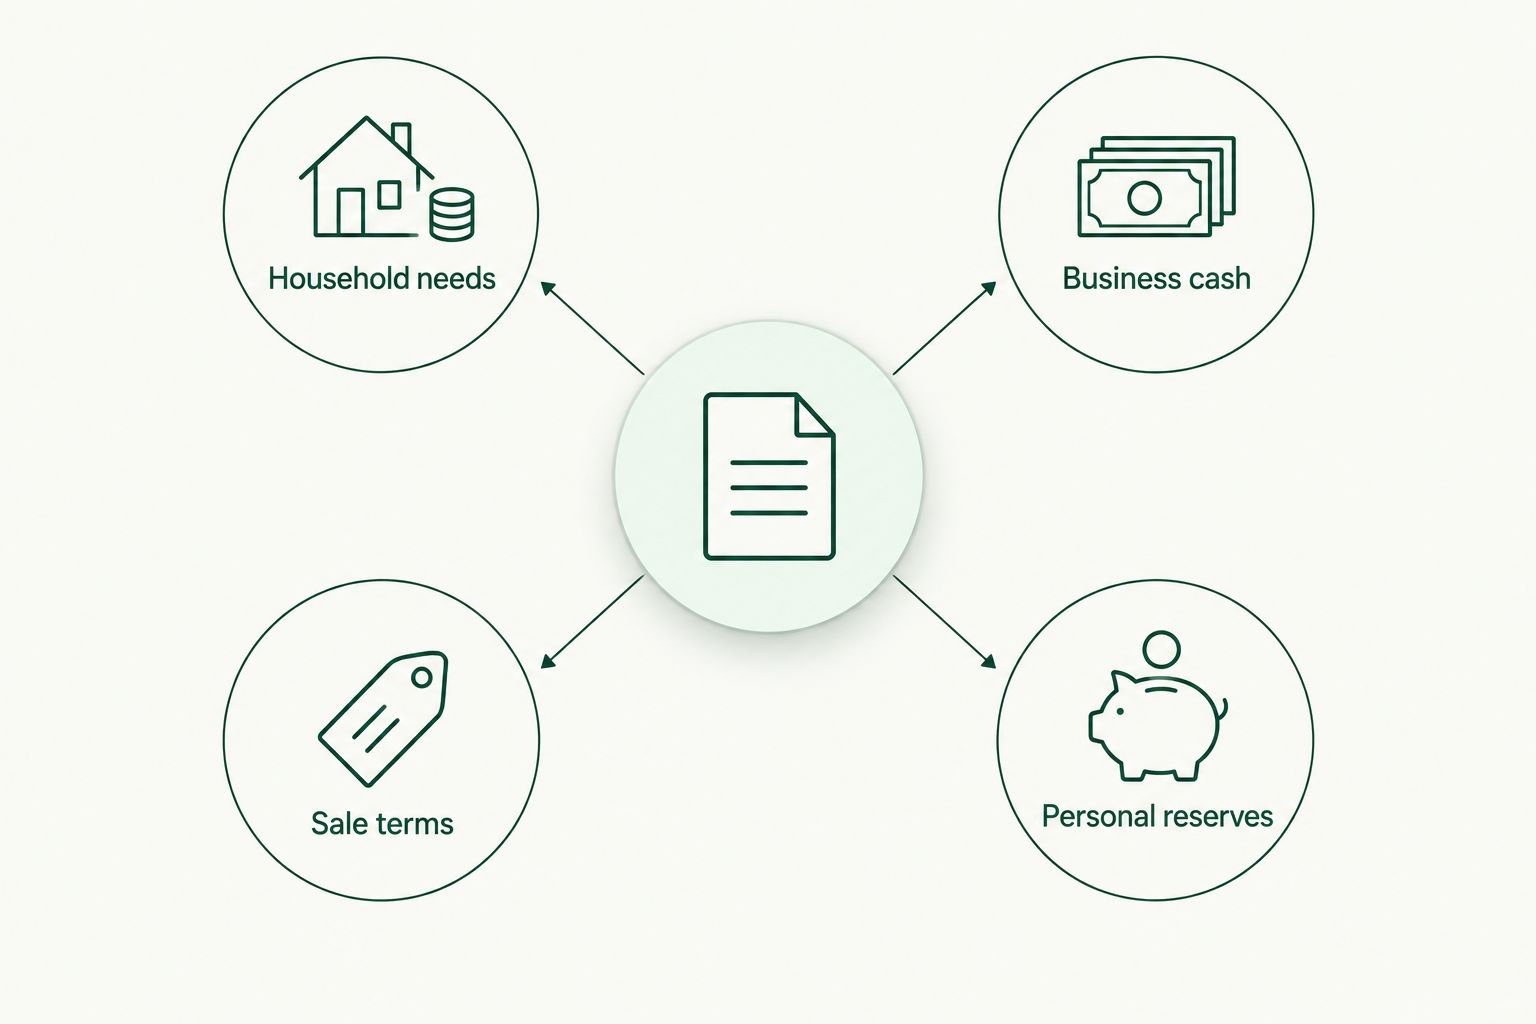
Give prospective advisors the same information so their proposed scopes are comparable. Start with these four parts; sensitive documents belong in an agreed secure sharing process.
Household needs
Bring 12 months of household spending records as a starting point. Separate recurring expenses from unusual purchases, and identify spending currently paid through the business that needs review after your departure.
Business cash
Request a 90-day business cash-flow forecast from the people responsible for your books and operations. Keep payroll, operating reserves, debt payments, and proposed buyer payments visible rather than treating the bank balance as sale-ready cash.
Sale terms
Summarize the proposed buyer, ownership interest, closing payment, future payments, and any continuing role. Mark assumptions as assumptions; an informal conversation is not a signed obligation.
Personal reserves
Identify which assets you already hold outside the company and which obligations remain attached to you. Your advisor needs to distinguish accessible money from company value and promised future payments.
Test the payment schedule, not just the sale price
Ask your advisor to compare 3 payment scenarios: payments arrive as agreed, payments arrive late, and payments stop. These are planning exercises, not predictions or claims about how employee sales usually perform.
For each scenario, identify which household expenses rely on buyer payments. Then ask your attorney and lender which protections, guarantees, restrictions, and remedies apply to the proposed documents.
A familiar employee is still a buyer. Trust does not answer whether the business can fund operations and purchase payments while supporting your continuing financial needs.
Tax work also needs a named owner. The case for hiring a tax strategist starts with the transaction questions requiring analysis, not revenue alone; define the scope with your tax professional and keep tax conclusions separate from the financial advisor's planning assumptions.
For a sale considered in 2026, have the tax professional identify applicable rules and filing responsibilities before you rely on projected net proceeds. Do not substitute a general article or an advisor's credential for transaction-specific tax work.
Ask these questions before signing an engagement
Use the answers to compare responsibility, not presentation quality. Request a written scope and identify any separate professionals you still need.
- What will you deliver before I accept sale terms? Ask for named outputs, such as a household cash-flow analysis and a list of unresolved assumptions.
- How will you assess future buyer payments? Require a distinction between money received and money still exposed to buyer performance.
- Who coordinates with my CPA and attorney? Name the person responsible for communicating changes.
- Which services are excluded? Check transaction execution, valuation, lending, tax preparation, and ESOP responsibilities explicitly.
- How are you compensated? Request the current written fee schedule and any relevant conflicts.
- What triggers an update? Include changes to closing timing, financing, ownership structure, or your post-sale role.
An advisor who clearly identifies exclusions gives you actionable information. An engagement that leaves responsibilities vague leaves you managing the gaps.
Which advisor should you choose?
Choose the advisor who can connect the proposed employee sale to your personal financial requirements before you accept the terms. For Northern Colorado owners, VIMSmallBusiness is a service-fit option for fee-only planning and succession coordination, with separate specialists handling the transaction.
Choose planning-only work when you need a defined decision project. Add ESOP-specific expertise when that structure is under evaluation, and treat post-sale investment management as a separate decision.
Your 2026 shortlist should end with written responsibilities, not a collection of reassuring conversations.
FAQ
What's the best financial advisor for selling my business to employees?
Choose an advisor whose written scope covers your personal cash flow, seller-payment risk, and coordination with transaction professionals. Northern Colorado owners can consider the named local option in this guide for fee-only planning and succession coordination, not transaction execution.
Can a financial advisor sell my company to an employee?
Financial planning does not itself include brokering a business sale. Establish separately who handles buyer negotiations, legal documents, financing, valuation, and closing.
Is selling to employees the same as an ESOP?
No. A direct purchase by an employee or employee group is different from an ESOP, a retirement plan that holds employer stock for employees.
Do I need both a CPA and a financial advisor?
You need responsibility assigned for both transaction tax work and personal financial planning. Confirm each engagement's scope; a financial advisor's CPA credential does not establish that the firm prepares tax returns.
Should I hire an advisor before agreeing on the sale price?
Engage personal financial planning before accepting terms you intend to rely on for your exit. The payment schedule, continuing obligations, and household cash needs matter alongside the headline price.
What should I bring to the first advisor meeting?
Bring household spending records, business cash-flow information, proposed sale terms, and a summary of assets and obligations outside the company. Agree on a secure process before sharing sensitive documents.
How do I compare what employee-sale advisors charge?
Compare current written fee schedules against the same requested scope. Separate planning, investment management, transaction, legal, valuation, and tax work so exclusions remain visible.
One last thing
Your departure as an employee, your transfer of ownership, and your release from financial obligations are different events. Write down each event separately, then ask the responsible professional what makes it effective.
A sale announcement does not answer all three. Neither does a financial plan; this article is educational, not personalized financial, tax, or legal advice.