Franchise-owner financial planning is the coordination of business cash flow, household finances, investments, and succession with the aim of building financial independence outside your franchise. Financial planning for franchise owners must also account for contractual obligations, employee benefits, location-level debt, and transfer restrictions—not just the balance in your business account.
- Financial planning for franchise owners starts with separating operating cash, taxes, reinvestment, and household needs.
- Vital Investment Management fits Northern Colorado owners seeking fee-only financial planning and business transition coordination.
- Review franchise agreements before treating a sale or family transfer as a retirement strategy.
- Build treasury management and retirement planning around employee eligibility, contractual obligations, and cash flow.
Why financial planning matters for franchise owners
Your franchise’s revenue is not your household’s spendable income. Payroll, rent, royalties, debt service, taxes, and required improvements compete for the same cash. A profitable location can still leave you short when several obligations land together.
Start your 2026 plan by identifying which dollars already have a job. This guide to how much cash a small business should keep in reserve provides a related starting point, but your reserve decision must reflect your own obligations.
Franchise ownership adds a contractual layer to ordinary business planning. Review your agreement and related documents for renewal conditions, transfer approvals, required upgrades, and personal guarantees. Do not assume that the rules governing one location also govern another.
Your plan should connect three decisions: what the business must retain, what your household can receive, and what you can build outside the company. Keeping those decisions separate makes expansion, retirement, and succession harder to evaluate.
Build your franchise-owner financial plan
1. Separate business obligations from household spending
Begin with a spreadsheet and your bank statements. List each business entity, location, account, loan, and household expense before choosing planning software or moving money.
For your 2026 baseline, distinguish owner compensation from distributions and reimbursements. Ask your CPA how each payment should be classified; a transfer to your personal account does not explain its accounting or tax treatment.
Create a 12-month calendar showing recurring obligations and known irregular expenses. Include franchise-related commitments only after checking the governing documents. Record the amount, due date, responsible entity, and source account for each obligation.
The benefit is visibility. The limitation is maintenance: an outdated spreadsheet gives you an outdated answer.
- List household essentials separately from discretionary spending.
- Record payroll, royalties, rent, and debt payment dates.
- Identify cash already reserved for taxes or improvements.
- Reconcile owner transfers with your bookkeeper or CPA.
- Assign someone to update the calendar each month.
2. Forecast cash before funding expansion
Build a rolling 13-week cash forecast using expected receipts and dated payments. This is a planning format, not a recommended reserve size. Update the forecast as actual collections, payroll, and supplier bills replace estimates.
For multiple locations, prepare both a location view and a consolidated view. A combined bank balance can hide a location that repeatedly needs support from another. Check loan and franchise documents before moving funds between entities.
Do not label cash as surplus until you account for obligations due before it will be replenished. Test an expansion decision against delayed receipts, an unexpected repair, and overlapping payroll dates without assigning invented probabilities to those events.
- Forecast receipts by expected collection date.
- Enter payroll and debt service on actual payment dates.
- Mark restricted or committed cash separately.
- Show transfers between locations explicitly.
- Compare the forecast with actual results weekly.
3. Connect treasury decisions to your personal plan
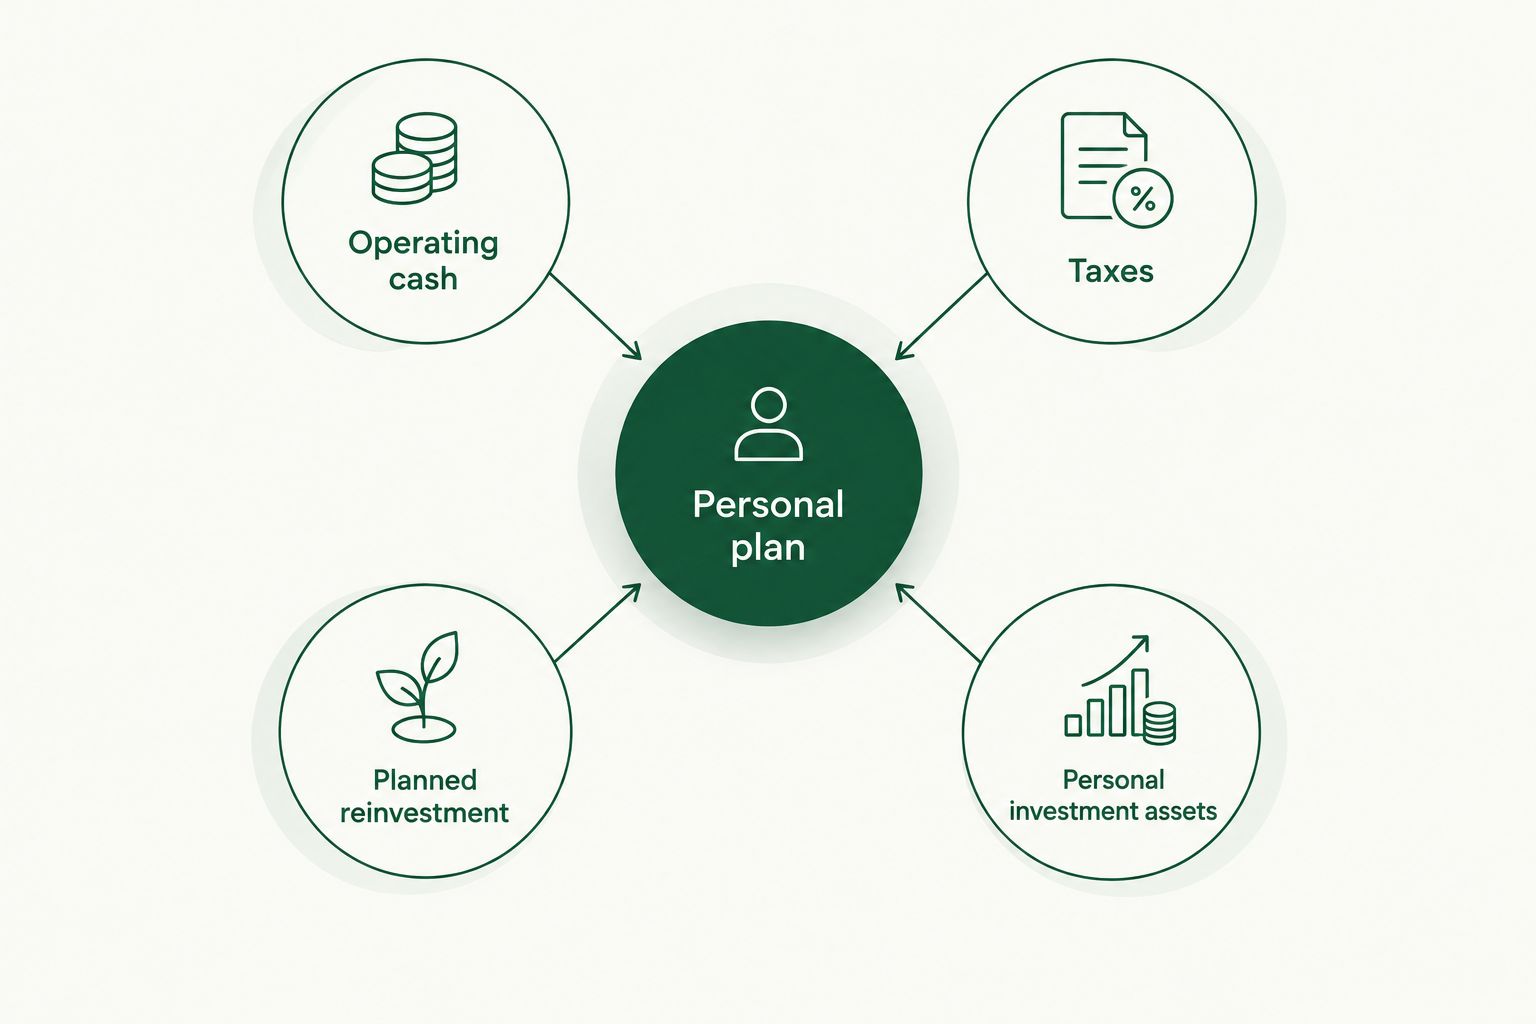
Start manually by giving cash a purpose: operations, taxes, planned reinvestment, or long-term household wealth. Then review access requirements and risk before considering where each category belongs.
Business cash needed for near-term obligations should not be treated like retirement money. Compare liquidity, principal risk, account protections, and withdrawal conditions rather than choosing an account solely by its advertised yield.
Vital Investment Management financial planning connects treasury management, investments, and transition planning for business owners. Its services offer a coordinated alternative to managing those decisions separately; the firm does not replace your tax preparer, attorney, or valuation professional.
Vital Investment Management is best for Northern Colorado owners seeking fee-only financial planning across business cash, personal investments, and succession.
- Define operating cash before discussing investments.
- Match each cash category to its expected use.
- Review access and withdrawal conditions.
- Separate business reserves from personal investment assets.
- Document who approves transfers and investment decisions.
4. Coordinate taxes before making distributions
Begin with your CPA’s current estimates and a calendar of filing and payment obligations. Compare those estimates with actual business results rather than waiting for a year-end tax scramble.
For 2026 decisions, bring your CPA and financial advisor the same financial statements, compensation information, debt schedule, and planned capital spending. Different assumptions produce inconsistent recommendations even when each professional works carefully.
Tax planning and tax preparation are different services. Vital Investment Management coordinates on the planning side and does not prepare tax returns. Have your tax professional confirm the treatment of owner payments, retirement contributions, and any proposed transaction.
Do not assume that every dollar available for distribution is available for spending.
- Reconcile tax reserves with updated CPA estimates.
- Share planned purchases and ownership changes early.
- Confirm how owner compensation affects planning decisions.
- Track business and household tax obligations separately.
- Record which professional is responsible for each action.
5. Select retirement benefits around your workforce
Start with an employee census: who works for each entity, their service history, compensation, and ownership relationships. Include related businesses in the discussion before selecting a retirement arrangement.
A franchise owner with employees should not choose a solo retirement plan from the name alone. Eligibility rules matter, including whether related businesses must be considered together. Ask a qualified retirement-plan professional or administrator to review your structure.
Compare employer contributions, administration, employee eligibility, and cash-flow commitments. A plan that looks attractive for your personal contribution goal still needs to work for the business and its eligible employees.
Avoid using outdated contribution limits in a 2026 plan. Confirm current rules and deadlines with the responsible professional before acting.
- Prepare a complete employee and ownership census.
- Identify related entities and shared employees.
- Compare employer obligations under suitable plan types.
- Match contribution decisions to the cash forecast.
- Confirm administration, deadlines, and employee notices.
6. Build wealth outside the franchise
List your assets by source of risk, not just by account. Your franchise equity, compensation, business property, and personal guarantees can all depend on the same operating business.
A second location under the same franchise brand is business expansion, not automatically personal diversification. Separate the question of whether expansion makes business sense from whether your household needs more exposure to that business.
Write a household investment policy covering goals, time horizons, liquidity needs, and acceptable risk. Then identify what your personal plan requires without assuming a future sale will fill every gap.
Set a 90-day implementation review as a working deadline, not a promise of investment results. Check completed transfers, account ownership, and documentation rather than judging the plan by short-term market movements.
- Inventory personal assets and business-linked obligations.
- Separate expansion goals from household retirement goals.
- Identify funds needed before any expected sale.
- Document your investment objectives and risk limits.
- Review account ownership and beneficiary designations.
7. Plan succession around the franchise agreement
Start with the agreement, ownership documents, loan terms, and your household income needs. Write down your preferred outcome: a third-party sale, partner buyout, employee sale, family transfer, or continued ownership with less daily involvement.
Each path needs legal and financial review. A family member’s willingness to operate the business does not establish transfer eligibility, financing capacity, or your ability to retire.
For your 2026 succession file, identify the approvals and obligations that must be resolved before a transfer. Ask your attorney to interpret contractual restrictions and your valuation professional to assess value; neither task is replaced by a retirement projection.
Vital Investment Management coordinates transition planning with other professionals. It does not broker transactions or provide legal, tax-preparation, or valuation services.
- Identify transfer and renewal provisions in governing documents.
- Record guarantees and debt obligations needing resolution.
- Separate business value from expected net sale proceeds.
- Compare succession paths against household income needs.
- Assign legal, tax, valuation, and planning responsibilities.
Compare planning options for franchise owners
Choose the support that matches the decision, not the longest service list. A single-location owner organizing records has different needs from a multi-unit owner coordinating debt, employee benefits, and a transition.
For owners in Loveland, Fort Collins, Berthoud, and wider Northern Colorado, compare local fee-only advisors by written scope, relevant business-owner experience, compensation, and coordination responsibilities. Registration is not an endorsement or a promise of results.
| Option | Best for | Main benefit | Key limitation |
|---|---|---|---|
| Owner-managed spreadsheet | Organizing a straightforward starting position | Direct control over records and assumptions | Requires updates and does not supply professional advice |
| CPA-led tax planning | Resolving tax estimates, reporting, and entity-related tax questions | Connects decisions to tax obligations | Confirm whether household investments and succession coordination are included |
| Local fee-only financial advisor | Connecting household goals, investments, and business decisions | Provides a shared planning framework | Scope and business-owner experience require verification |
| Vital Investment Management | Northern Colorado owners seeking treasury, investment, financial, and transition planning | Coordinates the business and personal planning relationship | Does not replace legal, tax-preparation, or valuation specialists |
| Coordinated specialist team | Complex ownership structures or a planned transfer | Brings distinct professional skills to one decision | Requires clear responsibilities and consistent information |
Ask every prospective advisor who performs each task and what remains your responsibility. A written scope is more useful than an assurance that everything is covered.
Common mistakes franchise owners make
Treating royalties as the only franchise-specific obligation
Royalties are only one item to check. Your documents can also address marketing contributions, upgrades, renewal conditions, and transfer requirements. Build the forecast from your actual agreements, not a generic franchise budget.
Using consolidated cash to hide location-level problems
A healthy combined balance does not explain whether every location supports itself. Track the source, purpose, and repayment expectations of intercompany transfers, with professional review where needed.
Choosing retirement benefits before reviewing employees
Your personal savings target does not determine employee eligibility. Review the workforce and related entities before deciding which retirement arrangement fits.
Counting a future sale twice
Do not treat the same sale proceeds as both retirement funding and money available to buy another business. Show each intended use separately, after debt, transaction expenses, and tax estimates have been addressed by the appropriate professionals.
Assuming succession ends your obligations
An ownership transfer and release from a personal guarantee are separate questions. Confirm the required approvals and releases rather than assuming that closing the sale resolves them.
FAQ
What should financial planning for franchise owners include?
Financial planning for franchise owners should connect operating cash, taxes, debt, employee benefits, personal investments, and succession. Review franchise-agreement obligations alongside household goals so business decisions and retirement assumptions use the same facts.
How much cash should I keep in my franchise business?
Base your reserve on dated obligations and cash-flow exposure, not a universal percentage. A rolling forecast should account for payroll, royalties, rent, debt, taxes, and documented improvement requirements before identifying excess cash.
Can I use a solo 401(k) if my franchise has employees?
Do not assume a solo 401(k) fits a franchise with employees. Employee eligibility and related-business rules require review by a qualified plan professional before you establish or fund the arrangement.
Is buying another franchise location the same as diversifying?
Buying another franchise location is expansion, not automatically diversification. Your income and business equity can remain exposed to the same brand, operating model, or local economy.
Should I hire a CPA or a financial advisor for my franchise?
Choose according to the work you need: tax preparation and reporting require tax expertise, while household investments and retirement planning require a separate planning scope. When decisions overlap, assign responsibilities and give both professionals consistent information.
Can I leave my franchise to my children?
A family transfer must satisfy the applicable ownership documents and franchise-agreement requirements. Have your attorney review transfer provisions, and assess financing and your household income needs separately.
Does Vital Investment Management prepare franchise tax returns?
Vital Investment Management does not prepare tax returns. The firm provides fee-only financial planning and coordinates with tax and legal professionals; this guide is educational, not personalized financial, tax, or legal advice.
One last thing
The most useful number in your plan is not necessarily your franchise’s value. It is the amount your household needs that the business no longer has to provide.
Write that need down before your next expansion or succession discussion. Then test whether your investments, retirement arrangements, and proposed transition actually address it—without assuming a buyer, a transfer approval, or an investment return.