Medical practice owners’ financial planning is the coordination of practice cash flow, personal finances, retirement, and succession with the aim of supporting your life beyond clinical income. This 2026 guide separates money needed to run the practice from money available for your household, investments, and eventual transition.
- Financial planning for medical practice owners starts with collections, payroll, taxes, and household spending—not an investment account.
- Vital Investment Management offers fee-only financial planning, treasury management, and transition planning for Northern Colorado business owners.
- Choose retirement arrangements around your employee census and sustainable contributions, not the largest possible deduction.
- Build personal wealth outside the practice; treat future sale proceeds as a separate planning assumption.
Why financial planning matters for medical practice owners
Practice revenue is not the same as money you can spend. Collections must cover staff, facilities, equipment, debt, taxes, and reinvestment before you decide what reaches your household. Your financial plan needs to connect those obligations rather than treat the practice and your personal accounts as unrelated projects.
Start your 2026 review with a shared cash-flow picture. Separate clinical compensation, ownership distributions, and practice equity so you can see what supports your lifestyle today and what depends on a future transaction.
Vital Investment Management is a fee-only fiduciary and SEC-registered RIA in Loveland, serving Northern Colorado business owners. Vital Investment Management is best for Northern Colorado owners seeking fee-only financial planning alongside treasury and transition planning. That scope does not replace healthcare-specific legal counsel, tax preparation, or an independent practice valuation.
Build your plan in seven steps
1. Separate practice performance from household spending
Begin with your bookkeeping reports, bank statements, and a spreadsheet. Gather the previous 12 months of collections, operating expenses, debt payments, owner compensation, and distributions; this is a working review period, not a rule about how much history every practice needs.
Then build a household spending summary without counting transfers between your own accounts as expenses. Include personal debt payments, insurance, education commitments, and irregular spending you would still face if you reduced clinical hours.
For a group practice, identify which financial decisions require partner approval. A plan based on distributions you cannot authorize is not an executable plan.
Close this step with a baseline you can reconcile:
- Match practice collections to bank deposits and accounting reports.
- Separate salary or guaranteed payments from ownership distributions with your CPA.
- Record household spending independently of practice expenses.
- List personal guarantees and debts tied to the practice.
- Identify who can approve distributions, borrowing, and major purchases.
2. Build a treasury plan around collections and payroll
Use a spreadsheet to create a 13-week cash forecast. This is a recommended planning window for comparing expected receipts with upcoming obligations, not an industry reserve standard. Update uncertain collection dates instead of treating billed charges as cash already received.
Organize the forecast into four purposes: Operating cash, Tax reserves, Owner pay, and Long-term wealth. Keep money needed for near-term obligations separate from money you can leave invested; a higher account balance does not establish that cash is surplus.
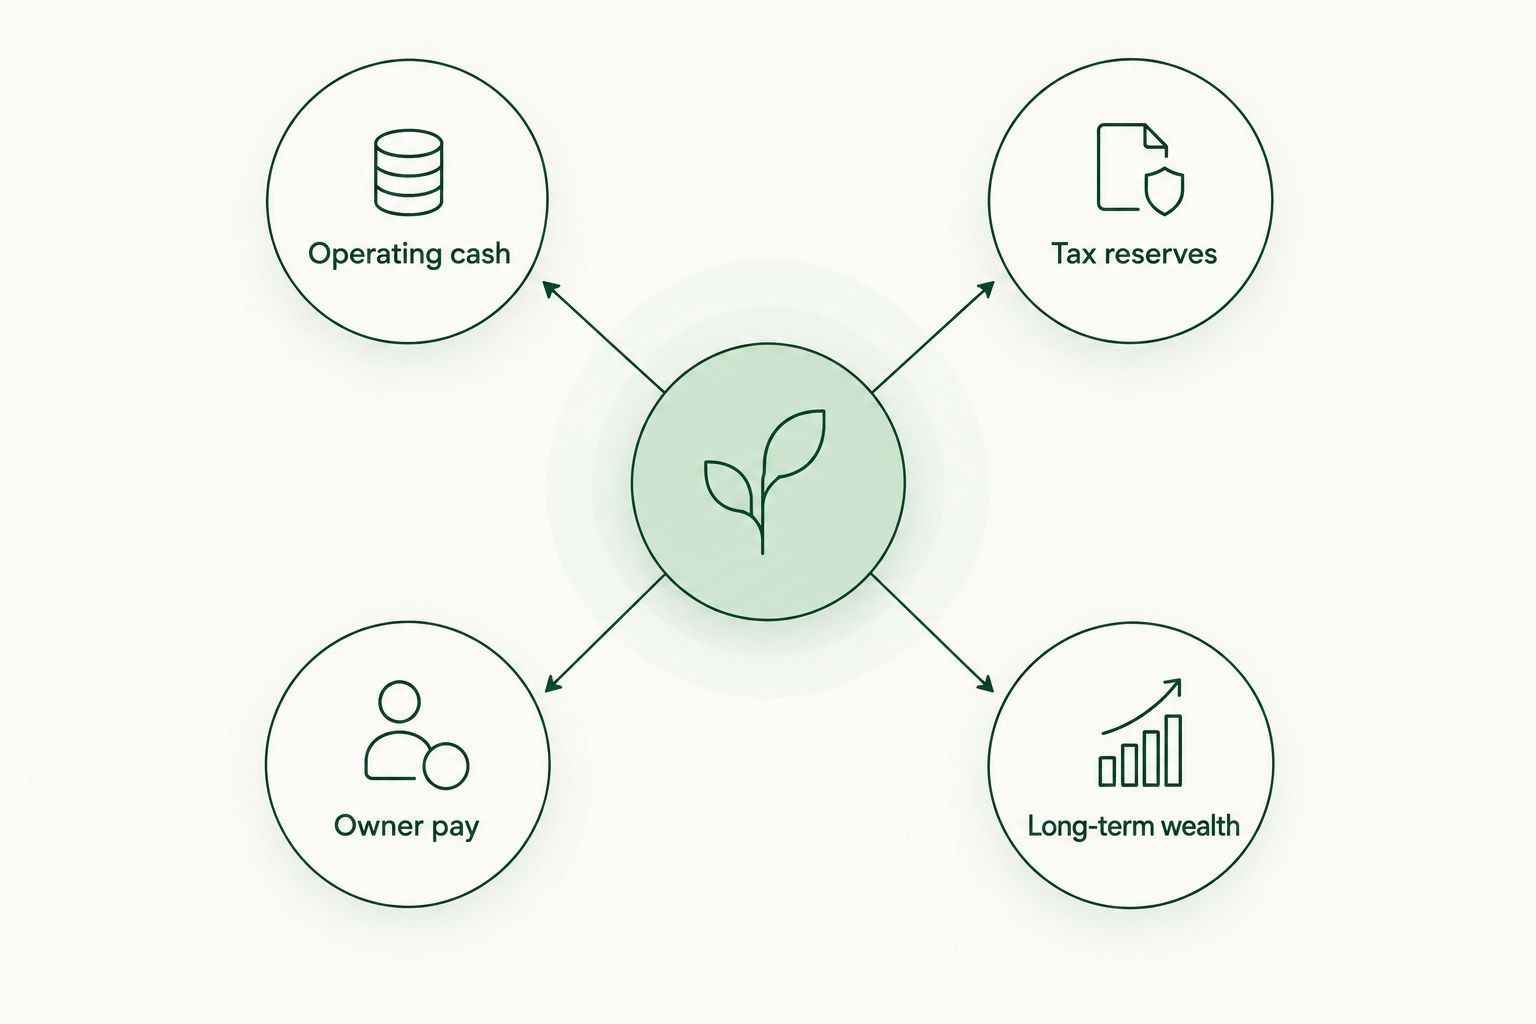
Treasury management can help organize this work, but the forecast comes first. The trade-off is ongoing maintenance: no account arrangement corrects an outdated view of payroll, receivables, or upcoming equipment spending.
- Enter payroll, rent, debt service, and known equipment payments by due date.
- Track expected collections separately from outstanding billed amounts.
- Model a 30-day collections delay as a planning exercise.
- Define the cash floor that must remain before owner distributions.
- Assign responsibility for updating the forecast and approving transfers.
3. Coordinate taxes before moving money
Start with a shared calendar and a list of planned transactions. Ask your tax preparer which payments, contributions, distributions, and equipment decisions need review before you act; an investment recommendation should not become an instruction to move practice money without that coordination.
For your 2026 plan, distinguish tax planning from tax preparation. Vital Investment Management provides financial planning and coordinates with tax professionals; it does not prepare tax returns. Its role belongs alongside your CPA’s work, not in place of it.
Have each professional identify the information needed from the other. Written responsibilities reduce the chance that everyone assumes someone else checked the consequences.
- Record estimated tax payment dates and the person calculating each payment.
- Ask your CPA to review how owner compensation and distributions are treated.
- Share planned retirement contributions before funding them.
- Review practice real estate and equipment decisions before signing commitments.
- Keep tax reserves distinct from money assigned to long-term investing.
4. Select retirement arrangements around your workforce
Begin with an employee census rather than a contribution headline. Record employee ages, compensation, service history, ownership, and existing retirement arrangements, then have a qualified plan professional evaluate eligibility and employer obligations.
A solo 401(k), SEP IRA, SIMPLE IRA, conventional 401(k), and cash-balance pension plan are not interchangeable. An owner-only plan is not a shortcut around eligible employees. A cash-balance plan is a defined-benefit pension arrangement, not simply another investment account; obtain specialist design and funding guidance before choosing it.
For 2026, evaluate the contribution you can sustain alongside payroll, taxes, debt, and personal savings. The largest possible contribution is not automatically the right commitment for your practice.
- Verify employee eligibility with the plan administrator.
- Compare owner contributions alongside required employee contributions.
- Ask who handles testing, filings, notices, and payroll coordination.
- Review existing plans across businesses with the relevant professionals.
- Obtain a written explanation of ongoing funding obligations.
5. Build personal wealth outside the practice
List your household assets, debts, practice ownership, and any separately held practice real estate. Then identify which assets you could actually use for retirement without selling the practice or borrowing against it.
Keep estimated practice value separate from liquid investments. A valuation is not cash in your account, and a proposed sale price does not establish what you would retain after debt, transaction expenses, and taxes.
Vital Investment Management offers investment management alongside financial planning. The benefit is connecting investment decisions to your wider cash-flow and transition needs; the limitation is that investment management cannot resolve uncertain practice value or guarantee a sale outcome.
- Separate accessible investments from practice equity and restricted interests.
- Set an investment policy around your time horizon and spending needs.
- Avoid assigning the same dollars to both reserves and retirement savings.
- Review investment risks alongside your dependence on clinical income.
- Test retirement readiness without assuming an unconfirmed practice sale.
6. Document continuity before you need a permanent exit
Start with an inventory of existing documents and responsibilities. Identify what happens to payroll, bank approvals, patient coverage, and partner decisions if you cannot work, then ask the appropriate professionals to address the gaps.
Disability coverage, professional liability coverage, life insurance, and buy-sell funding address different problems. Review the actual contracts with qualified professionals rather than assuming one policy or agreement covers every interruption.
For physician-owned entities, have healthcare counsel review ownership and transfer restrictions. Financial planning can identify the funding question; it does not determine whether a proposed ownership arrangement is legally permitted.
- Record authorized bank signers and backup payment approval procedures.
- Ask counsel to review buy-sell triggers and valuation language.
- Review disability definitions and coverage terms with an insurance professional.
- Check policy ownership and beneficiaries against the written agreements.
- Document who coordinates clinical coverage and operational continuity.
7. Model your transition before choosing a buyer
Write down what you want to change: clinical hours, management responsibilities, ownership, or all three. Retirement from patient care and a sale of ownership are separate decisions, even when you intend to make them together.
Compare the household consequences before choosing a transaction structure. An internal succession, partner buyout, family transfer, or outside sale needs its own legal, tax, valuation, and funding review; none should enter your plan as a guaranteed outcome.
Ask for a transition model that separates cash received at closing from deferred or conditional payments. Include any continuing employment, lease, or guarantee obligations so you can judge what you are actually leaving behind.
- Define your preferred clinical and management responsibilities after transition.
- Identify decision rights and restrictions in shareholder or operating agreements.
- Obtain an independent valuation when a transaction decision requires one.
- Model retained proceeds after debt, expenses, and taxes with your advisers.
- Test household spending against confirmed assets, not headline deal value.
Compare your planning options
Choose an approach by the work it covers and who remains accountable. Start manually if you need to organize records; add professional coordination when decisions cross practice operations, household finances, retirement, and transition. No single role replaces the entire team.
| Option | Best for | Main advantage | Key limitation |
|---|---|---|---|
| Owner-led spreadsheet and document folder | Establishing your baseline | Keeps assumptions and records visible | You maintain the work and coordinate every handoff |
| CPA-led tax planning | Tax projections and transaction tax questions | Connects proposed decisions to tax obligations | Confirm separately who owns household and investment planning |
| Local fee-only financial planner | Connecting practice decisions to personal goals | Brings cash flow, investments, retirement, and transition into one plan | Scope varies; verify healthcare-specific needs separately |
| Qualified retirement-plan specialist | Evaluating employee coverage and plan design | Addresses administration and funding requirements | Does not replace a household financial plan |
| Healthcare attorney and independent valuation professional | Ownership agreements and transaction preparation | Addresses legal structure and practice value within each professional’s scope | Requires coordination with tax and financial planning |
For owners in Loveland, Fort Collins, Berthoud, and wider Northern Colorado, compare local fee-only advisers on written scope, coordination responsibilities, and relevant experience. Ask who maintains the cash-flow assumptions and who follows up when another professional needs information. A meeting without assigned responsibilities leaves you as the project manager.
Common mistakes medical practice owners make
Treating billed charges as distributable cash
A busy schedule does not establish that payroll, taxes, and debt are covered. Base distributions on collected cash and your forecast, then check the resulting practice balance against obligations already committed.
Choosing a retirement plan before reviewing employees
Starting with the owner’s desired deduction reverses the decision. Review the employee census, eligibility, administration, and funding requirements before selecting an arrangement or making a contribution.
Counting the practice twice
Do not count practice equity as both a retirement asset and a separate source of future spending without showing the transaction that converts it into usable cash. Keep operating income, estimated equity value, and eventual net sale proceeds distinct.
Leaving continuity entirely to the buy-sell agreement
An agreement does not answer every operational question. Payroll approvals, patient coverage, document access, and insurance funding need explicit owners alongside the legal documents.
Assuming every adviser owns the whole plan
Your CPA, attorney, financial planner, and plan administrator have different responsibilities. Record who calculates, reviews, authorizes, and implements each decision so a recommendation does not stop at the meeting notes.
FAQ
What should financial planning for a medical practice owner cover?
Financial planning for a medical practice owner should connect practice cash flow, household spending, taxes, retirement, investments, continuity, and succession. Keep practice operating needs separate from money available for personal goals.
Do I need both a CPA and a financial adviser for my practice?
Use both when you need tax work and coordinated household financial planning, with a written division of responsibilities. Confirm who prepares returns, calculates tax payments, maintains projections, and coordinates investment and retirement decisions.
Can I use a solo 401(k) if my medical practice has employees?
A solo 401(k) is an owner-only arrangement and cannot exclude employees who must be covered under applicable eligibility rules. Have a qualified plan professional review your workforce, ownership, and related businesses before adopting one.
How much cash should my medical practice keep in reserve?
Set your reserve from actual obligations and collection timing rather than a universal percentage. Use a cash forecast to test payroll, debt payments, taxes, equipment commitments, and a collections delay before distributing excess cash.
Should I count my practice value toward retirement?
Include estimated practice equity separately from liquid retirement assets. Model usable proceeds only after reviewing debt, transaction expenses, taxes, payment terms, and the uncertainty of completing a sale.
Can Vital Investment Management prepare my practice tax returns?
Vital Investment Management does not prepare tax returns. Its financial planning work can be coordinated with your tax preparer, while tax preparation remains with the appropriate professional.
When should I start planning to sell my medical practice?
Start when you begin considering a change in clinical work, management duties, or ownership. Early planning lets you review agreements, household spending needs, valuation, and continuity before deciding on a transaction.
One last thing
Test whether your plan works without a sale. For your next 2026 review, build a version that uses only assets you already control and income assumptions you can explain. Then show practice-sale proceeds separately, with their conditions attached.
That exercise identifies what depends on the practice and what does not. Your next decision becomes clearer: strengthen reserves, fund personal assets, change spending, or prepare the transition more deliberately.